Estate Planning
Estate Planning — All content on The Advisors Table.
Episodes
 Solo
CRA Takes 54% Of Your RRSP When You Die (Unless You Do This)
How a $1 million RRSP can create a $500,000+ tax bill at death – and the little-known planning strategy that may help families keep far more of their wealth.
- RRSP
- Retirement Planning
- Beneficiary Designations
 Solo
Estate Planning Explained: Will vs. Trust In Canada
How wills, beneficiary designations, joint ownership, and trusts actually control your assets in Canada – and why many families discover critical estate planning gaps only after a crisis occurs.
- Estate Planning
- Wills & Estates
- Trust Planning
 Guest
Most Wills Fail. Here's Why
Why most wills fail in Canada – not due to drafting, but because they become outdated, clash with laws, and fail to reflect real family and asset changes over time and across jurisdictions
- Wills & Estates
- Estate Planning
- Executor Planning
 Episode
Being An Executor Can Cost You Personally
How choosing an executor is far more than an administrative decision – and how personal liability, CRA reassessments, and estate risks can last years.
- Executor Planning
- Wills & Estates
- Estate Planning
 Solo
CRA Tax Rule That Wipes Out Inheritances
How death can trigger layers of tax that erase millions in family wealth – exposing business owners and estates to probate, liquidity crisis, and devastating double and triple taxation without proper planning.
- Estate Planning
- Post-Mortem Planning
- Probate
 Episode
CRA Bill That Destroys Wealth After Divorce
Why family law, tax rules, and poor documentation can turn parental help into an unintended wealth transfer.
- Wealth Transfer
- Estate Planning
- Case Study
 Solo
CRA Takes 80% When You Die
How dying with an incorporated business can trigger layers of tax that devastates family wealth – and why post-mortem planning is critical before it's too late.
- Estate Planning
- Post-Mortem Planning
- Probate
 Episode
The $10M Tax Bill When A Business Owner Dies
How one founder built a $50M company but left his family exposed to over $10 million in tax, probate delays, and succession chaos due to missing estate planning.
- Estate Planning
- Post-Mortem Planning
- Succession Planning
Posts
Should You Put Assets In Your Kids' Names? Why Wealthy Canadian Families Never Do
Wealthy Canadian families almost never put assets in their kids' names. Here's why, how a family trust works instead, and the timing decision worth $1.3 million.
Do You Need A Holding Company In Canada? The 5 Signs
A holding company can save hundreds of thousands in tax – or add needless complexity. Learn the five signs it makes sense, from surplus cash and investments to asset protection and business sales.
The RRSP Trap: Why CRA Takes 54% Of Your RRSP When You Die (And How To Stop It)
A $1 million RRSP can trigger a $540,000 tax bill at death. Learn the little-known strategy that can legally reduce that tax burden and preserve more wealth for your family.
Will vs. Trust: Which One Actually Controls Your Assets In Canada?
Most Canadians think their will controls everything they own – but beneficiary designations, joint ownership, probate, and tax rules often determine where assets actually go.
3 CRA Powers Coming in 2026 That Every Canadian Needs to Know
The CRA's new 2026 audit powers — compelled sworn testimony with no transcript, $50/day penalties without a court, and reassessment clocks frozen indefinitely. Here are the three every Canadian needs to understand.
One Mistake Killed His $5M Deal — Why the Wrong Team Destroys Business Sales
Selling your business? One wrong hire and hidden tax traps can kill the deal. Why regular accountants fail at business-exit tax planning — and how to build the deal team that protects your sale.
CRA’s 5 Most Dangerous Weeks: What TEBA Means for Your Next Audit
What is TEBA, and why does it make February–March the most dangerous weeks for a CRA audit? How the CRA's March 31 year-end drives aggressive reassessments — and a 3-phase plan to protect yourself.
$800K Tax Bill That Should’ve Been $0 — The 5 Mistakes That Cost This Business Owner Everything
Discover the 5 critical errors that turned a $0 tax bill into an $800K disaster for a business owner. Learn how to protect your company from CRA reassessments, audits, and massive penalties.
Visual Guides
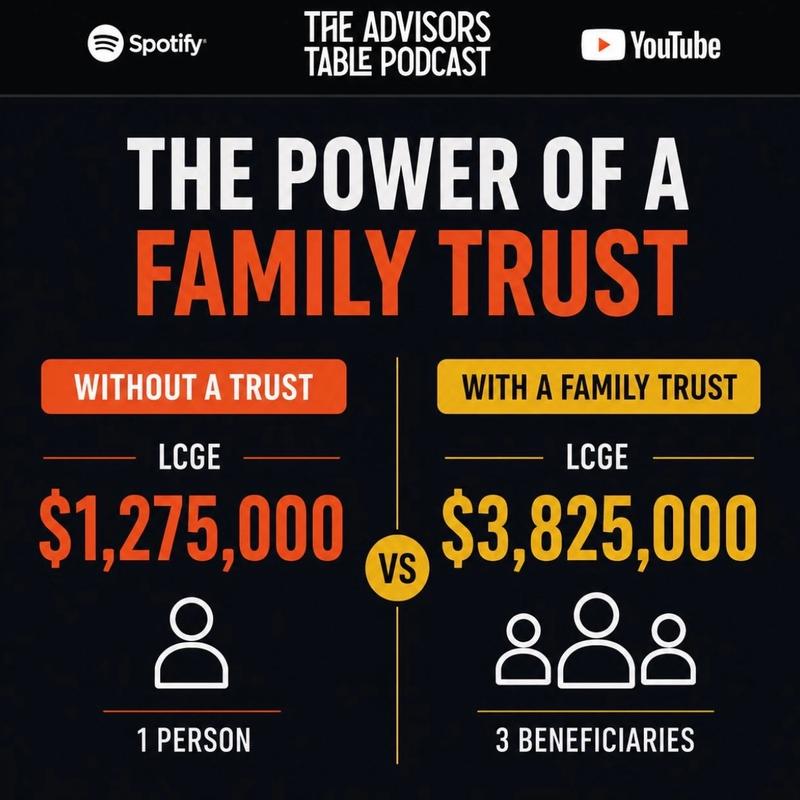
The Power Of A Family Trust
Same business. Same sale. Same CRA rules. The only difference is how the shares were held. Without a trust: $1,275,000 sheltered through LCGE. With a family trust and three kids: up to $3,825,000 sheltered. The math speaks for itself.
CRA Is Still Auditing A Tax That No Longer Exists
The Underused Housing Tax was rescinded under Bill C-15 for 2025 and subsequent years. No filings required. No tax owed. But the CRA is still auditing taxpayers who were exempt from the old rules and didn't file the paperwork – for a tax they were never going to owe in the first place. The minimum penalty? $1,000 for individuals and $2,000 for corporations. Per property. Per year. That is not compliance work. That is revenue collection through paperwork penalties on a regime the parliament has already thrown out.
Will Vs. Trust Explained
Most Canadian think their will handles everything. It doesn't. Your RRSP goes to whoever is on the beneficiary form. Your jointly-owned house goes to the surviving owner. Your will? It only controls what's left over. Here's what a will CAN'T do: • Save you tax • Control when your kids get their money • Help if you're incapacitated • Protect assets from creditors A family trust does all of that. And the difference can be hundreds of thousands of dollars.
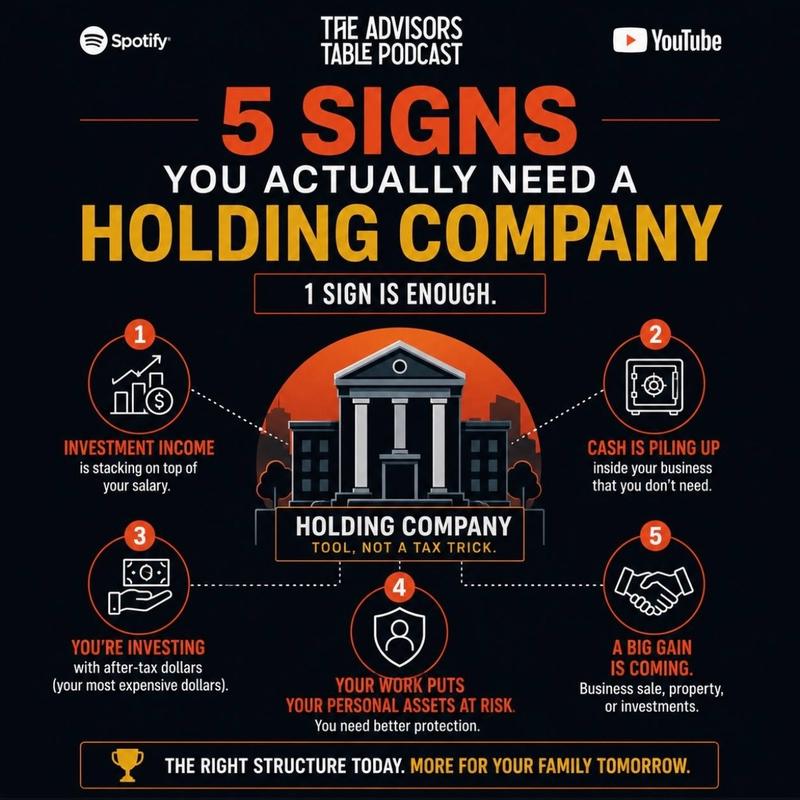
5 Signs You Actually Need A Holding Company
Not everyone needs a holding company – but for the right person, it can save hundreds of thousands in tax and protect everything you've built. Here are 5 signs it might be time to consider one.
Why The Wealthy Never Gift Their Kids Anything
The wealthiest families in Canada almost never put anything in their kids' names. Not the company. Not the property. Not the investments. It isn't because they don't trust their kids. It's because a gift is the one financial move you can never take back. Swipe for what they do instead, and the $1.3 million difference it made for one family.