Beneficiary Designations
Beneficiary Designations — All content on The Advisors Table.
Episodes
 Solo
CRA Takes 54% Of Your RRSP When You Die (Unless You Do This)
How a $1 million RRSP can create a $500,000+ tax bill at death – and the little-known planning strategy that may help families keep far more of their wealth.
- RRSP
- Retirement Planning
- Beneficiary Designations
 Solo
Estate Planning Explained: Will vs. Trust In Canada
How wills, beneficiary designations, joint ownership, and trusts actually control your assets in Canada – and why many families discover critical estate planning gaps only after a crisis occurs.
- Estate Planning
- Wills & Estates
- Trust Planning
Posts
The RRSP Trap: Why CRA Takes 54% Of Your RRSP When You Die (And How To Stop It)
A $1 million RRSP can trigger a $540,000 tax bill at death. Learn the little-known strategy that can legally reduce that tax burden and preserve more wealth for your family.
CRA Bare Trust Rules 2026: Joint Accounts & Family Explained
CRA Bare Trust Rules 2026: Joint Accounts & Family Explained
Are joint bank accounts a bare trust? With Bill C-15 now law, here's what the 2026 CRA bare-trust rules mean for joint accounts, parent–child accounts, in-trust-for accounts, and a parent on title of a home — in plain English.
Visual Guides
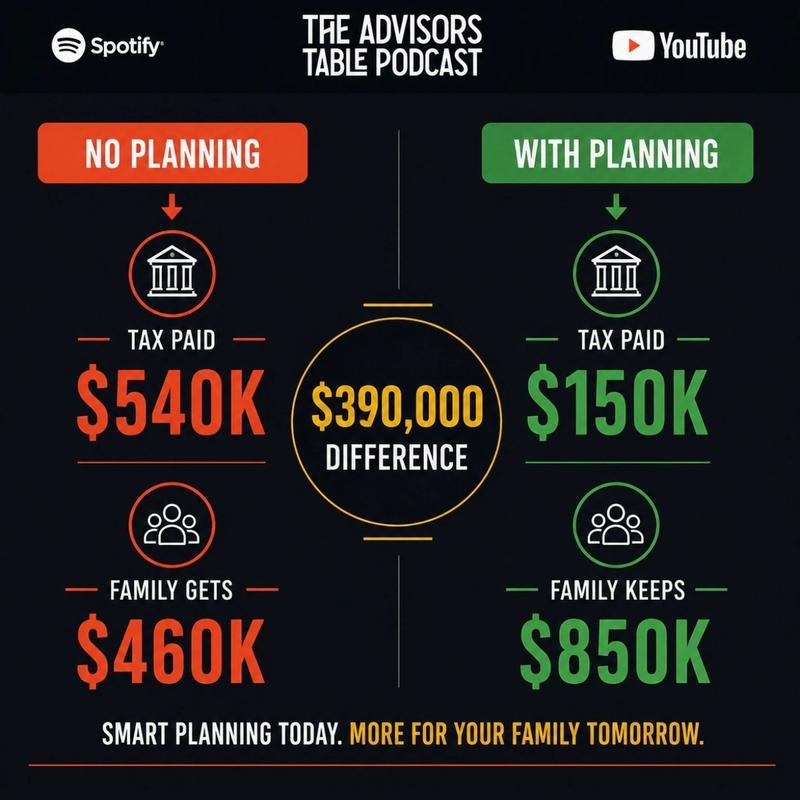
Same $1M RRSP, $390,000 Difference
Same $1M RRSP. Same family. $390,000 difference.
CRA Takes 54% Of Your RRSP When You Die
CRA can take 54% of your RRSP when you die. Not your business. Not your real estate. The retirement savings you built one paycheque at time. Here's what almost nobody tells you: your entire RRSP lands on your final tax return as income, all in one year. On a $1M RRSP, combined with the deemed disposition on the rest of your estate, the tax can hit $540,000. But there's a provision in the Income Tax Act that can redirect your RRSP to a minor child or grandchild, taxed at their rate instead of yours. It can drop the total tax to around $150,000. That's a $390,000 difference. Same RRSP. Same family. Same law.